Investing with TERRA
Three programmes, three investment logics, the same anchor in Saint-François.
Three operations, three patrimonial angles
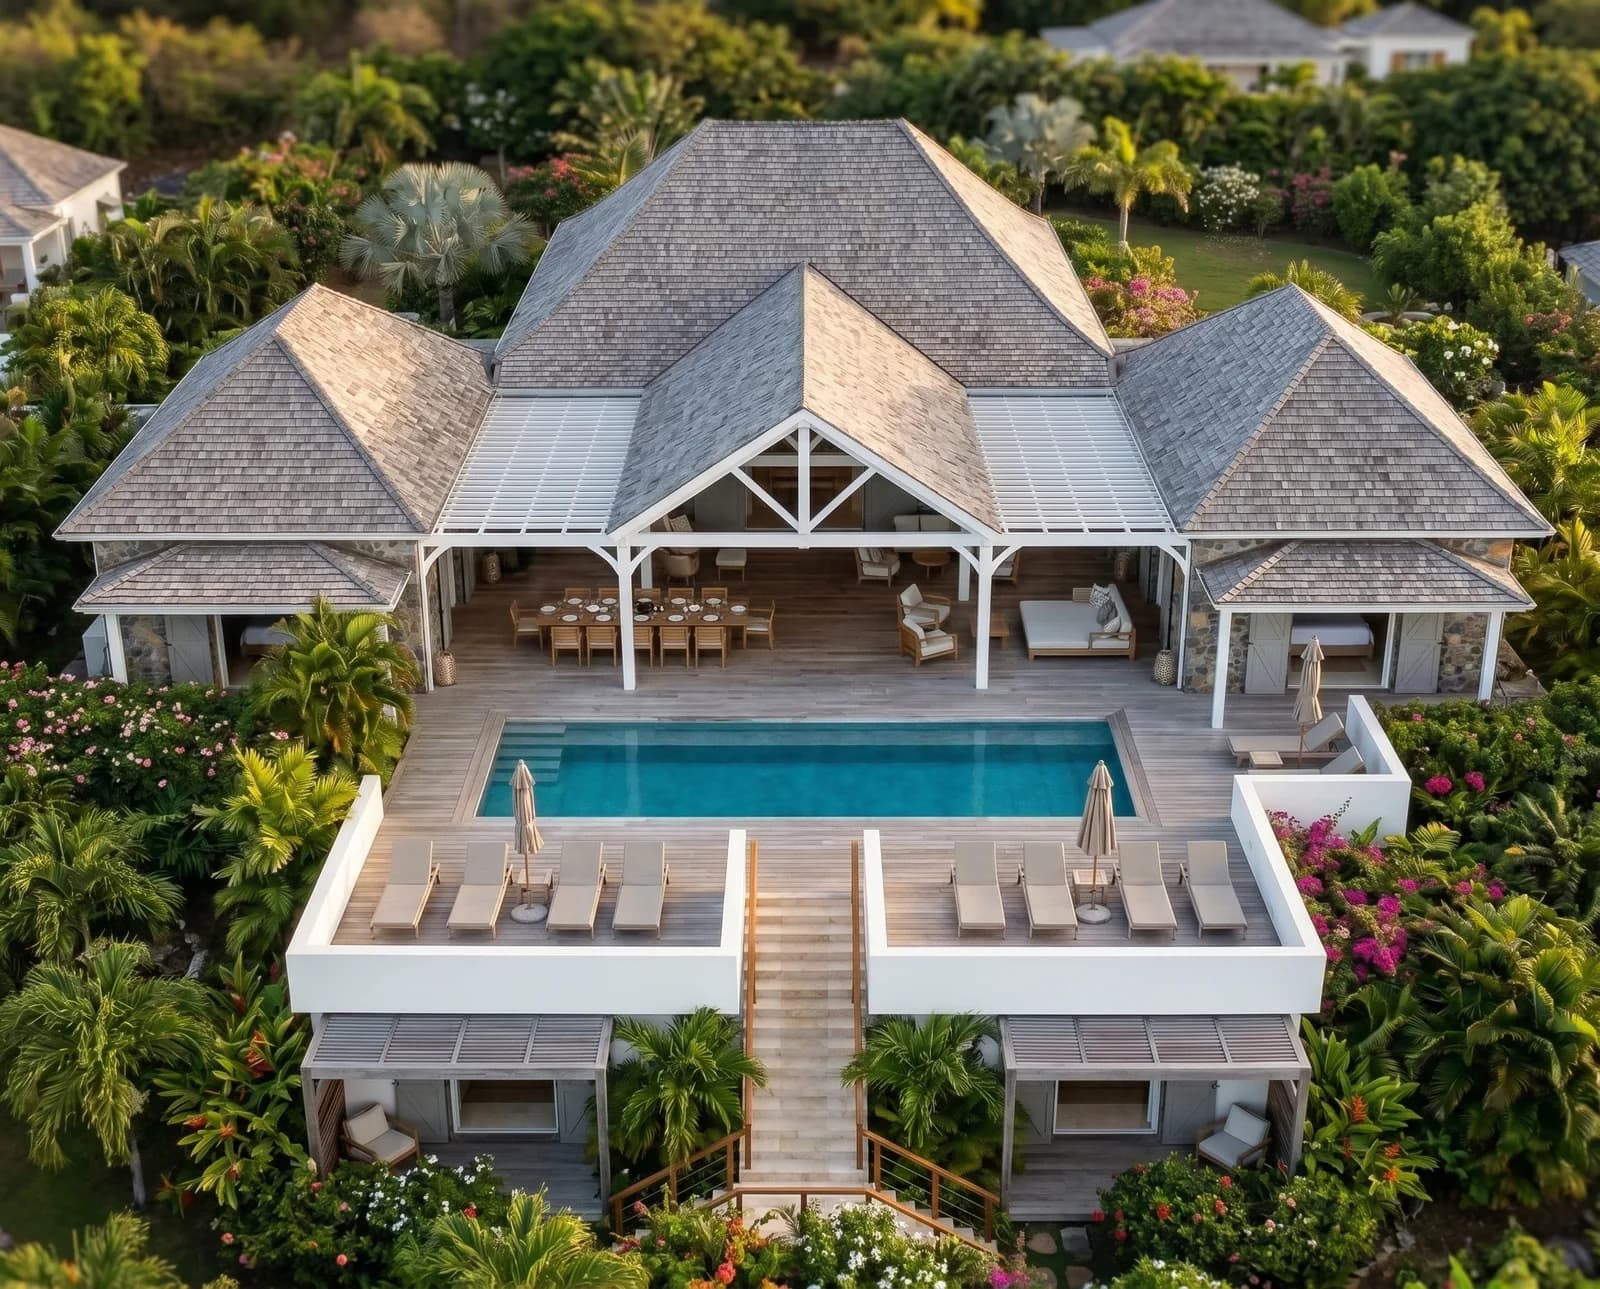
Belles Rives
Final phase · 7 villas · VEFA
From €1,200,000 excl. VAT
Seven villas on sale, final phase: VEFA and building plots. Plateau dominating the Saint-François lagoon. May qualify for the overseas tax credit (CIOP), subject to conditions.
- Immediate acquisition
- May qualify for the CIOP, subject to conditions
- Final phase in commercialization
Rosebud
24 villas · 180 & 250 m²
From €1,530,000 excl. VAT*
Twenty-four single-storey villas, 180 and 250 m², at Anse Champagne. Sales open in January 2027.
- Interest list open
- Sales opening January 2027
- Four price tiers, €8,500 to €12,000 excl. VAT per m²
Bel Arbre
Saint-François · Programme under study
Programme under study — interest list open.
- Interest list open
- Information coming soon
- Rare land in Saint-François
The CIOP: 35% for a company subject to corporate tax
The tax credit for productive investment in overseas territories (CIOP, article 244 quater W of the French Tax Code) benefits the company operating the investment in Guadeloupe. Rate: 35% (corporate tax) or 38.25% (income tax). The credit is disbursed in stages as construction progresses.
Tax credit under article 244 quater W of the French General Tax Code. Eligibility is subject to compliance with legal conditions, including operating requirements and, where applicable, prior approval; each project is assessed on a case-by-case basis.
35 %
Corporate tax rate in Guadeloupe (art. 244 quater W CGI)
15 ans
Operating period for buildings
1 M€
Prior approval threshold
Villa acquired through a French corporate-tax operating company
Illustrative example: Belles Rives villa at €1,450,000 excl. VAT
Assumptions
- —Villa price: €1,450,000 excl. VAT (lots 8, 9, 22 or 34), land and construction; 8.5% VAT not included.
- —Buyer: company subject to corporate tax (IS), operating the villa as furnished holiday letting for 15 years.
- —Tax credit base: price excl. VAT, land and construction (TERRA PROMOTION position, to be validated case by case with your advisors).
- —Excluding bank financing, acquisition costs and income tax.
The CIOP on the base
| Base retained (price excl. VAT) | €1,450,000 |
| Tax credit (35%, company subject to IS) | €507,500 |
| Net capital committed after credit | €942,500 |
Rate reference: BOI-BIC-RICI-10-160-20, § 130.
The tax credit is not taxable income (BOI-BIC-RICI-10-160-30, § 10).
Timeline: fund calls and equity release
| Stage | VEFA fund calls, cumulative | Tax credit | Net capital committed, cumulative |
|---|---|---|---|
| Foundations — year 1 | 35%: €507,500 | −€355,250 | €152,250 |
| Weathertight stage — year 1 | 70%: €1,015,000 | −€101,500 | €558,250 |
| Completion — year 2 | 95%: €1,377,500 | – | €920,750 |
| Handover — year 2 | 100%: €1,450,000 | −€50,750 | €942,500 |
Fund calls: legal ceilings for VEFA (French Construction Code, art. R.261-14).
35% tax credit (article 244 quater W of the French General Tax Code), accruing 70% at completion of foundations, 20% at the weathertight stage and the balance at handover (BOI-BIC-RICI-10-160-20, § 150). The portion exceeding the tax due is refunded immediately (BOI-BIC-RICI-10-160-30, § 50).
Construction duration: illustrative.
In this example, net capital committed stands at €942,500 at handover.
Rental yield: three scenarios
| Gross annual rental income (assumption) | Gross yield on price (€1,450,000) | Gross yield on net capital (€942,500) |
|---|---|---|
| €60,000 | 4.1% | 6.4% |
| €75,000 | 5.2% | 8.0% |
| €90,000 | 6.2% | 9.5% |
Gross yields, before operating expenses (management, maintenance, insurance, property tax), income tax and financing. Rental income figures are assumptions and vary by occupancy, season and rates; they do not constitute a promise or guarantee of income.
With bank financing (25% deposit)
- —Deposit of 25%: €362,500
- —Loan of 75%: €1,087,500
- —Rate of 4.0%, 20-year term, level annuities
- —The tax credit, once refunded, is applied to early repayment of the loan, reducing the outstanding balance to €580,000
- —Subject to bank approval
| Deposit | €362,500 |
| Tax credit (35%) applied to early repayment | €507,500 |
| Loan balance after early repayment | €580,000 |
| Annual payment, after early repayment | €42,677 / yr |
| Gross annual rental income (assumption) | Cash flow after payment, before expenses and tax | Relative to deposit |
|---|---|---|
| €60,000 | €17,323 | 4.8% |
| €75,000 | €32,323 | 8.9% |
| €90,000 | €47,323 | 13.1% |
At 25% deposit, the tax credit (€507,500) exceeds the deposit (€362,500). Applied to early repayment, it reduces the debt to €580,000 and the annuity to approximately €42,700 per year. Each year, the annuity also repays capital (approximately €19,500 in year one), which increases the company's net assets.
Cash flows before operating expenses (management, maintenance, insurance, property tax), income tax and arrangement fees. The rate, term and financing ratio are assumptions, depending on the lender and borrower profile. During construction, the buyer bears fund calls and interim interest until the credit is refunded.
Illustrative, non-contractual worked example. The tax credit under article 244 quater W of the French General Tax Code is conditional upon compliance with legal requirements, including operating the investment for the required period and, where applicable, obtaining prior approval (for investments exceeding €1,000,000). Non-compliance results in clawback of the credit. The base, timeline and amount of the credit depend on each project and must be validated with your advisors.
Get in touch
Our team guides you in choosing the programme suited to your situation. Response within 24 hours.